How we help
Built around your VA benefit and your next move.
Your Certificate of Eligibility, first
The Certificate of Eligibility (COE) is VA's proof that you qualify. It also shows how much entitlement you have. Entitlement is the amount VA guarantees for you. VA says you can request it three ways: online, through a lender, or by mail on VA Form 26-1880. We can pull it with you so you know where you stand before you look at homes.
Using your benefit more than once
Many veterans think the VA loan is a one-time thing. It isn't always. We walk through your past VA loans and tell you what may still be available. Read how a veteran couple did it in Keys Down the Street.
Your pay, counted the way it's paid
Active-duty pay isn't just a base number. We'll show you how your Leave and Earnings Statement (LES) is read and what the underwriter will look at. The underwriter is the person at the lender who decides whether your income qualifies.
We show up for veterans
Outside the office, our team supports veterans in the community. In October 2026 we were an Honor Guard Sponsor of the 7th Annual Heroes in the Shadows Stand Down at El Monte VFW Post 10218.
The whole picture
A VA loan isn't always the right fit. We'll compare it with other loans so you can choose with your eyes open. Start with our VA home loans guide: eligibility, the funding fee and what's different in California.
Your loan options
More than one way to buy.
There's no single right loan for military and veterans. We look at your income, savings and plans, compare these side by side, and tell you plainly which fits, including when it's not CalHFA.
FHA
Insured by the Federal Housing Administration (FHA), with more flexible credit rules. HUD says FHA isn't only for first-time buyers, and the down payment can be a gift from family or an employer.
Read our guideConventional
Most follow Fannie Mae and Freddie Mac guidelines. Options like HomeReady and Home Possible are for buyers with lower incomes, with limits set by area, and some options are for first-time buyers.
Read our guideVA
For eligible service members, veterans and surviving spouses, whatever job you do now. VA says its guaranty, in most cases, lets you buy with no down payment.
Read our guideEach loan has its own eligibility rules. Subject to credit approval and underwriting.
Down payment help
CalHFA works with VA loans too.
CalHFA, California's housing finance agency, offers first-time buyer loans and down payment help through approved lenders like New American Funding. Colleen Olivas is a CalHFA Preferred Loan Officer, and we'll tell you plainly whether you qualify.
- $210,000 CalHFA's income limit for its first mortgages and MyHome (2026) in San Bernardino County. Source: CalHFA income limits, effective 06/30/2026. All counties
- 3 yearsIf no one on the loan has owned and lived in a home in the past 3 years, you may count as a first-time buyer
These programs are loans, not gifts. Funds are limited and rules can change, so we confirm what's open before you plan. Subject to eligibility and program availability.
Your team
You have a team of loan officers who work with military and veterans.
Call the office and we'll match you with the right person, or pick someone you'd like to talk to.
Free, and yours to keep
Read at your own pace, wherever you're stationed.
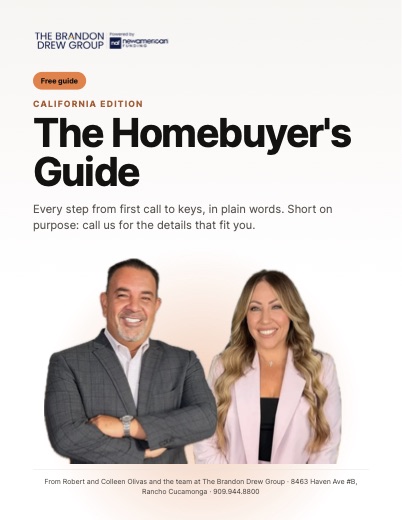 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
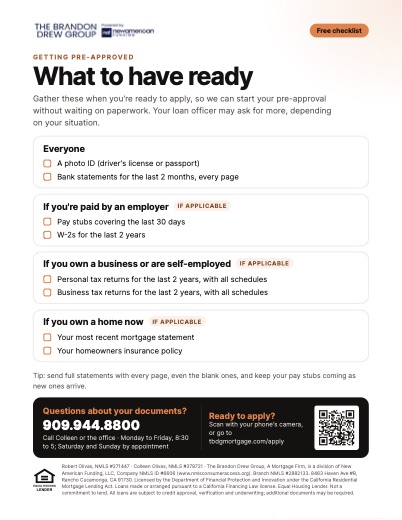 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
More programs worth asking about
- VA home loans: guaranteed by the U.S. Department of Veterans Affairs for eligible veterans, service members and some surviving spouses. VA says the home must be for your own personal occupancy. With full entitlement, VA says you don't have a loan limit, as long as you can afford the loan and the appraisal supports the price, and your lender still has to approve you.
Questions we hear
Can I use my VA benefit more than once?
Often, yes. VA lists the ways, including after you sell the home and pay off the loan, or once, by repaying the loan in full while you keep the home. Your Certificate of Eligibility shows what's left. Our story Keys Down the Street follows a veteran couple who reused their VA benefit to buy a second home.
What is bonus entitlement?
VA describes it as the amount it agrees to pay your lender, on a loan over $144,000, if you don't pay the lender back. VA explains that if you have full entitlement, bonus entitlement usually covers 25% of the amount a lender is willing to loan you. We'll look at your Certificate of Eligibility and tell you what we see.
How do I get my Certificate of Eligibility?
Three ways, per VA: request it online, ask a lender to request it for you, or mail VA Form 26-1880. We can request it with you.
Does my military pay count in full?
For conventional loans, Fannie Mae's guidelines say the lender may include the full amount of your monthly base pay and allowances as qualifying income, as long as nothing shows they'll be lowered or stop. Active duty has no set minimum history. Guard and Reserve need 12 months. The LES must be dated within 120 days of the note date, which is the date you sign the loan. VA and FHA loans have their own rules, and lenders can add stricter ones, so we'll confirm what applies to your loan.
I'm a surviving spouse. Can I use the VA loan?
Possibly. VA says an unremarried spouse of a Veteran who died in service or from a service-connected disability can qualify. We can help you request your Certificate of Eligibility to confirm.
What if my discharge wasn't honorable?
You may still be eligible. VA decides case by case. We can help you request your Certificate of Eligibility to find out.
We also thank
Disclosures
We are not affiliated with or endorsed by any law enforcement, fire, military, health care or school agency. VA home loans are guaranteed by the U.S. Department of Veterans Affairs; we are not affiliated with or endorsed by VA. We are not affiliated with or endorsed by HUD, FHA, Fannie Mae or Freddie Mac. Programs have eligibility rules, funds are limited, and terms can change without notice. Not all applicants will qualify. This is not a commitment to lend.