
Keys down the street from their first grandchild
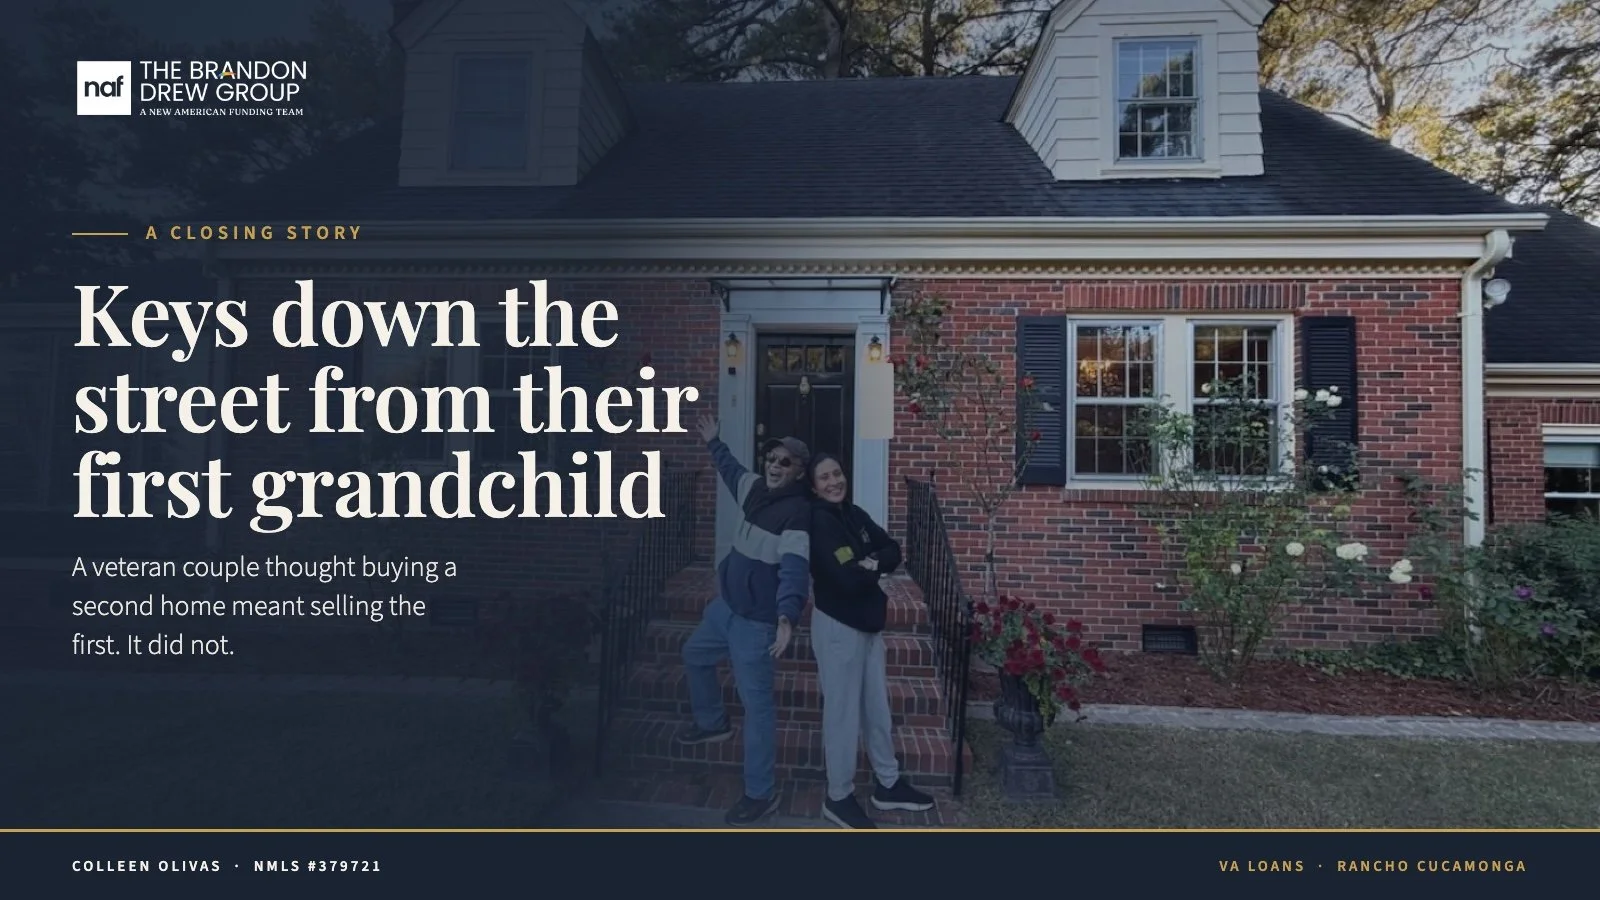
Colleen Olivas's veteran clients at the closing of their second VA home, down the street from their daughter, Inland Empire
A veteran couple thought buying a second home meant selling the first. It did not. Colleen Olivas on the VA benefit most families have never heard of.
This closing meant a lot to me. My clients are veterans, buying for the second time, and when we first talked they believed what most people believe: that to buy the next house, you sell the one you are in. They also had a reason to move that had nothing to do with square footage. Their daughter lives down the street from this house, and she is expecting their first grandchild.
What they did not know is that a VA home loan benefit does not get used up by one purchase. They could keep their current home, move out and rent it, and still buy this one with their VA benefits, using what is called bonus entitlement. Because they had enough entitlement left, the down payment on this home was small. Many VA buyers put nothing down at all.
“They had no idea that they could keep their current property, vacate it as a rental, and still purchase utilizing their VA benefits.”
What "entitlement" means
The VA does not lend the money. It guarantees part of the loan, which is why lenders can offer veterans a loan with no down payment and no monthly mortgage insurance. That guarantee is your entitlement. When you buy a home with a VA loan, part of it is tied up in that loan. The part that is left is your remaining, or bonus, entitlement, and it can be used to buy another home while you still own the first one.
How much you have left depends on the size of your current VA loan and the loan limit for the county you are buying in. If what remains covers the new loan, you can buy with no down payment. If it covers most of it, the difference becomes a down payment, and it is often far smaller than people expect. That is what happened here.
You must live in the new home. You do not have to sell the old one.
The first home can become a rental, and in many cases the rent can even help you qualify for the new loan. We walk through the occupancy rules, the county loan limit and the entitlement math before anyone falls in love with a house, so the answer is known on day one and not on day twenty.
Three numbers I ask for on day one
I started my career in underwriting, so I read a file the way an underwriter will. On a second-time VA purchase, three things early tell us whether the down payment is zero, small, or something to plan for. Robert reviews the structure before it goes to underwriting. Two senior lenders on every file.
Questions veterans ask us
Can I use my VA benefit more than once?
Yes. Entitlement is restored when a VA loan is paid off, and remaining entitlement can be used while you still own the first home.
Do I have to sell my current home to buy with VA again?
No. You can keep it and rent it out. You must intend to occupy the new home as your primary residence.
Will I need a down payment on the second VA loan?
It depends on your remaining entitlement and the county loan limit. Some buyers put nothing down; others put down a small amount that covers the gap.
Does the rent from my first home count as income?
Often, with documentation and a reserve requirement. We check it before you make an offer.
Is there mortgage insurance on a VA loan?
No monthly mortgage insurance. There is a one-time VA funding fee, which some veterans are exempt from.
“This family is so excited to move right down the street from their daughter, who is having their first grandchild.”
Bring your Certificate of Eligibility, or just your questions. We will show you the numbers before you look at a single listing.
Start hereRancho Cucamonga, CA 91730
Colleen Olivas, NMLS #379721, co-founder of The Brandon Drew Group, a division of New American Funding. Former underwriter. CalHFA Lending Hero. Lending alongside Robert Olivas since 1988.
Last reviewed October 27, 2026. Program rules change; we verify current VA guidelines on every file.
The Brandon Drew Group, a division of New American Funding, LLC, NMLS #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2590251. Colleen Olivas NMLS #379721. Equal Housing Lender. VA loans are subject to VA eligibility, entitlement, occupancy and underwriting requirements; terms and down payment, if any, depend on remaining entitlement and county loan limits. This is not a commitment to lend. Clients' names and details withheld; story shared with permission.