How we help
Built around your shifts and your overtime.
We read your paystubs the way an underwriter will
An underwriter is the person at the lender who decides whether your income counts. Overtime, court time and special-assignment pay show up on your stubs in different ways. Before you shop, we sit down with your last two years and tell you what we think the underwriter will see. That way nothing surprises you in the middle of the loan.
Weekends, by appointment
Our office is open Monday to Friday, 8:30 AM to 5:00 PM; Saturday and Sunday by appointment. If you work days, swings or nights, tell us what works and we'll book around your schedule.
One list, asked once
You already fill out enough reports. We give you one clear list of what we need, and we ask for it once.
A look at HUD's Good Neighbor Next Door
HUD has a program for law enforcement officers that sells certain homes at a discount. It is real, and it is also limited, so we'll tell you honestly what to expect. The FAQ below explains how it works.
Your loan options
More than one way to buy.
There's no single right loan for law enforcement. We look at your income, savings and plans, compare these side by side, and tell you plainly which fits, including when it's not CalHFA.
FHA
Insured by the Federal Housing Administration (FHA), with more flexible credit rules. HUD says FHA isn't only for first-time buyers, and the down payment can be a gift from family or an employer.
Read our guideConventional
Most follow Fannie Mae and Freddie Mac guidelines. Options like HomeReady and Home Possible are for buyers with lower incomes, with limits set by area, and some options are for first-time buyers.
Read our guideVA
For eligible service members, veterans and surviving spouses, whatever job you do now. VA says its guaranty, in most cases, lets you buy with no down payment.
Read our guideEach loan has its own eligibility rules. Subject to credit approval and underwriting.
Down payment help
If you need down payment help: CalHFA.
CalHFA, California's housing finance agency, offers first-time buyer loans and down payment help through approved lenders like New American Funding. Colleen Olivas is a CalHFA Preferred Loan Officer, and we'll tell you plainly whether you qualify.
- $210,000 CalHFA's income limit for its first mortgages and MyHome (2026) in San Bernardino County. Source: CalHFA income limits, effective 06/30/2026. All counties
- 3 yearsIf no one on the loan has owned and lived in a home in the past 3 years, you may count as a first-time buyer
These programs are loans, not gifts. Funds are limited and rules can change, so we confirm what's open before you plan. Subject to eligibility and program availability.
Your team
You have a team of loan officers who work with law enforcement.
Call the office and we'll match you with the right person, or pick someone you'd like to talk to.
Free, and yours to keep
Read at your own pace, on your days off.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
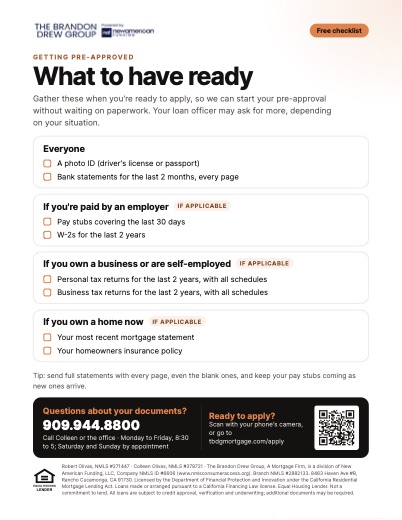 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
More programs worth asking about
Questions we hear
Does my overtime count as income?
It can. For conventional loans, Fannie Mae's guidelines recommend a two-year history of overtime. They also say a shorter history, but no less than 12 months, may be considered acceptable when positive factors offset it. And if your overtime has been going down, the lender needs to confirm it has leveled off. Lenders can add stricter rules of their own. Bring your last two years of paystubs and W-2s and we'll tell you how we think it will be counted.
I work a second job. Will that count?
Many lenders look at the same kind of history for any extra income: how long you've done it, and whether it's steady. We'll look at your tax returns and paystubs together and tell you how an underwriter is likely to see it. We won't promise a result before we've seen the paperwork.
What about shift differential, court pay or special-assignment pay?
We don't have a single rule to quote for those, and we won't make one up. How they count depends on how your department pays them and how long you've received them. Show us your stubs and we'll explain how the underwriter will see each line.
What is Good Neighbor Next Door?
It's a HUD program for law enforcement officers, pre-K through 12th grade teachers, firefighters and emergency medical technicians. HUD describes a discount of 50% from the list price of the home. You must work full time in the area the home serves, and you agree to live in the home for 36 months as your principal residence. The homes are limited, and the list changes weekly, so there may be few or none near us at any given time. You can search the current listings at HUD Home Store. If you find one you like, call us and we'll walk you through the loan side.
Is there a special loan for law enforcement?
Not one national loan. FHA, conventional, VA, CalHFA and GSFA are all open to qualifying buyers whatever their job, and we'll compare them side by side for you.
We also thank
Disclosures
We are not affiliated with or endorsed by any law enforcement, fire, military, health care or school agency. VA home loans are guaranteed by the U.S. Department of Veterans Affairs; we are not affiliated with or endorsed by VA. We are not affiliated with or endorsed by HUD, FHA, Fannie Mae or Freddie Mac. Programs have eligibility rules, funds are limited, and terms can change without notice. Not all applicants will qualify. This is not a commitment to lend.