Buyer guide with Colleen Olivas
My Anaheim Home: The City of Anaheim's First-Time Homebuyer Loan (2026)
By Colleen Olivas, NMLS #379721, who started in escrow and worked her way through every role in mortgages, up to underwriter. The Brandon Drew Group, a division of New American Funding Last reviewed November 2026
Quick answer
The City of Anaheim offers a loan to help first-time buyers with a down payment. The city's page says the program "offers a $50,000 loan to help with a down payment on a home." The city's portal says funding is limited, applications are first come, first served, and "the program may close at any time." You have to live in the home, buy inside Anaheim, meet the city's income limits, stay under the city's price limit, and finish an approved homebuyer seminar. The city told us it doesn't keep a preferred lender list. The city loan can only go toward your down payment, and it comes with rules about renting, refinancing and borrowing against the home, listed below. Next step: check your eligibility on the city's portal, then call us about the first mortgage. Subject to eligibility and lender approval.

On this page (7 sections)
What the program is
The City of Anaheim's First-Time Homebuyer Program page says the program "helps low- to moderate-income households buy a home by bridging the gap when prices and down payments would otherwise be out of reach." It "offers a $50,000 loan to help with a down payment on a home."
The city's flyer calls it the "My Anaheim Home" "First-Time Homebuyer Loan Program," under the city's Local Housing Trust Fund. City Council minutes from March 24, 2026 say it launched in late 2025 and provides a $50,000 loan as a second mortgage. A second mortgage is a second loan on the same home, behind your main (first) mortgage.
We are not putting the loan's interest rate, length or payment details on this page. The city sets them and they can change. Read them on the city's page, or call the city's housing office (contact details below). The city's adopted program guidelines (amended and adopted June 9, 2026) say "Repayment is due when the home is no longer owner-occupied, the property is sold or the title is transferred," and "Refinancing of the first mortgage is permitted only to lower the interest. Any cash-out refinancing will trigger repayment of the loan." They also say you "Must be pre-qualified for a fixed-rate First Mortgage," that the buyer "shall cover all closing costs," and that "non-occupant co-borrowers are not allowed." Read the guidelines.
Who can qualify
These are the city's rules, in the city's words. The page says you must:
- "Meet household income limits"
- "Not have owned a home in the past three years"
- "Buy a home within Anaheim (unincorporated Anaheim areas are ineligible)"
- "Live in the home as owner-occupant"
- "Choose an eligible property type (single-family, townhouse or condo)"
- "Stay within the maximum purchase price allowed"
- "Complete an approved homebuyer seminar"
The city's flyer adds that the seminar must be a "HUD-approved in-person seminar." The flyer says the home's price "cannot exceed the average home purchase price in Anaheim." The city's housing office told us by email on November 9, 2026 that the maximum sales price for the fourth quarter of 2026 is $946,371. The city gave this as the fourth-quarter 2026 figure, so ask for the current one before you make an offer.
The city's local preference. This is the City of Anaheim's own rule, not ours: "Priority is given to people who live or work in Anaheim for the past 12 months." The city does not say what happens to your place in line if you do not meet it. Ask the city.
"Unincorporated Anaheim areas are ineligible" means some addresses with an Anaheim mailing address may not count. Ask the city to confirm the address of any home you are looking at before you make an offer.
Income limits
The city's flyer sets the income limit at "Moderate Income (High Cost Area) 150% AMI." AMI means area median income. The flyer takes the figures from "HCD Area Median Income Limits - Fiscal Year (FY) 2026." Here are the household income limits the city's flyer lists:
| People in your household | Income limit on the city's flyer |
|---|---|
| 1 | $145,500 |
| 2 | $166,350 |
| 3 | $187,100 |
| 4 | $207,900 |
| 5 | $224,550 |
| 6 | $241,200 |
| 7 | $257,750 |
| 8 | $274,400 |
Source: the City of Anaheim's My Anaheim Home flyer. Open the city's flyer. The flyer says: "Income limits are provided by the California Department of Housing and Community Development (HCD) and are subject to change without notice."
These are the city's program limits. Other programs set their own limits, so check each one. The Council minutes describe the limit as household income "up to 150% of the Area Median Income (AMI) for Orange County." How a lender counts your income for the program is something to ask before you apply.
Funding and timing
The city's housing portal says: "The First-Time Homebuyer Program is currently accepting applications for down payment assistance. Funding is limited, and applications will be accepted on a first-come, first-served basis while funds remain available. The program may close at any time."
What that means for you:
- Check the portal before you plan around this loan. A program that is open today may not be open when you find a home.
- New applicants review eligibility first. The portal is available in English, Español and Tiếng Việt.
- Do not sign a purchase contract that depends on the city loan until you have the city's answer in writing.
City housing office contact (from the city's page): Housing & Community Development, 201 S. Anaheim Boulevard, Suite 1003, Anaheim, CA 92805. 714-765-4300, ext. 4810 (TTY: dial 711). residentialloans@anaheim.net. Monday to Friday, 8 a.m. to 5 p.m.
How it fits with a first mortgage, CalHFA and GSFA
The city loan is down payment help. You still need a first mortgage for the rest, and the city's guidelines say it must be a fixed-rate first mortgage. The city's housing office told us by email on November 9, 2026: "We do not keep a preferred lender list." Ask any lender whether it has reviewed the city's loan documents and can close a first mortgage alongside the city loan. We can help you get pre-approved for a first mortgage and compare CalHFA and GSFA options side by side.
Using the city loan with another assistance program. The city loan normally sits right behind your first mortgage. The city told us: "we are willing to subordinate if their loan is larger than our $50,000." Subordinate means the city loan moves behind the other assistance loan. So whether two programs fit on the same home depends on the other program's amount and its own rules.
CalHFA. The California Housing Finance Agency runs state programs, including CalHFA MyHome Assistance; see also our CalHFA page. CalHFA's MyHome program sheet says "MyHome must be combined with a CalHFA first mortgage and may be combined with other down payment and/or closing cost assistance programs but must remain in second lien position" (program sheet revised October 19, 2026). That is CalHFA's rule. Because MyHome has to stay right behind the first mortgage, the city loan would have to move behind MyHome. CalHFA's sheet sets the MyHome amount as a share of the home's price, and at the city's price limit that comes out well under $50,000. So as we read the two programs' rules today, MyHome and the city loan don't fit together on the same home. If you want both, ask the city first.
GSFA. The Golden State Finance Authority offers GSFA Platinum through participating lenders, and New American Funding is on GSFA's participating lender list. GSFA Platinum is repaid differently from CalHFA MyHome, so compare the whole package. The same city rule applies: the city told us it subordinates when the other assistance loan is larger than $50,000. Ask us to check the numbers for the home you want.
Every program has eligibility rules, funds are limited, and amounts and terms can change. Ask us for the current rules the day you call, and check the agency page too.
Rules that come with the city loan
The city sent us its loan document templates (the loan agreement, promissory note, deed of trust and disclosure). These are the rules in them that matter most to a buyer. Your own documents from the city are the final word, so read them before you sign.
- Down payment only. The loan agreement says the city loan "may only be used towards Homebuyer's down payment." It can't pay closing costs.
- You live there. You move in within 60 days of closing and confirm in writing each year that the home is still your main residence.
- No renting. Renting the home out, including short-term rentals like Airbnb or VRBO, isn't allowed. The city's housing director can approve a short rental of up to six months in a verified extreme hardship.
- No new loans against the home without the city's OK. The agreement says you can't add "any additional mortgage or deed of trust, including any line of credit," without the city's written consent. That includes a home equity line of credit (HELOC).
- Refinancing has limits. The city reviews any refinance of your first mortgage. It considers one only if it lowers your interest rate, isn't a cash-out refinance and meets the city's other conditions.
- Insurance. You keep full replacement-value, all-risk property insurance that names the City of Anaheim as a loss payee, and you send the city a copy each year.
- Selling. You tell the city in writing at least 30 days before you list the home, with an appraisal. You can sell at market value, and you repay the city loan from the sale, plus the city's loan servicing fee.
- When repayment is due. The city's housing office told us repayment is required at the end of the loan's term, when you sell, if you transfer the home without the city's approval, if you do a cash-out refinance, or if you no longer live in the home.
- Paying early. You can pay the city loan off early at any time without a penalty.
- If the owner dies. A surviving spouse or registered domestic partner can take over the loan and live in the home. Other heirs have to repay the city loan; the loan agreement says how long they have.
Questions to ask before you apply
Whichever lender you choose, ask:
- Has this lender's underwriting reviewed the City of Anaheim's loan documents, and has it closed loans with the city's program?
- Is the first mortgage a fixed-rate loan, as the city requires?
- Can the city loan sit together with another assistance program on the same home?
- How does the lender count my household income for the city's limit?
- When is the in-person seminar, and does the city accept it?
- What does the whole loan look like on one page: what I will owe, when, and to whom, for the first mortgage and the city loan together?
You can also talk with a HUD-approved housing counselor. Talk to more than one lender. That is good practice, and we say so even though we are a mortgage branch ourselves.
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
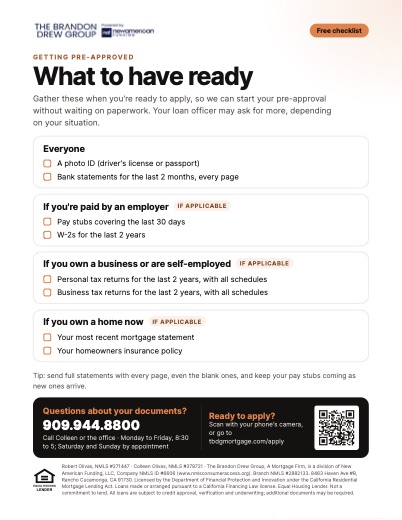 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
What is My Anaheim Home?
It is the City of Anaheim's First-Time Homebuyer Program. The city says it "offers a $50,000 loan to help with a down payment on a home." The city sets all other terms, so read its page for the current ones.
Is the program open right now?
When we read it on November 8, 2026, the city's portal said it "is currently accepting applications for down payment assistance," that funding is limited and first come, first served, and that "the program may close at any time." Check the portal the day you plan to apply.
Who is eligible?
The city lists these rules: meet household income limits; not have owned a home in the past three years; buy within Anaheim; live in the home as owner-occupant; choose a single-family home, townhouse or condo; stay within the maximum purchase price; and complete an approved homebuyer seminar. See the city's list.
→ Read: Debt-to-income ratio, explained
Do I have to live or work in Anaheim?
The city says "Priority is given to people who live or work in Anaheim for the past 12 months." That is the city's rule for who goes first. Ask the city how it works in practice.
→ Read: CalHFA program page
What is the income limit?
The city's flyer sets it at "Moderate Income (High Cost Area) 150% AMI." The flyer lists a figure for each household size; see the table above. The flyer says limits "are subject to change without notice." See the flyer.
→ Read: CalHFA program page
Does the city have a list of approved lenders?
No. The city's housing office told us on November 9, 2026: "We do not keep a preferred lender list." Ask any lender, including our branch, whether it has reviewed the city's loan documents and can close a first mortgage with the city loan. Call us and we'll tell you where that stands.
Can I use this with CalHFA MyHome or GSFA Platinum?
The city told us "we are willing to subordinate if their loan is larger than our $50,000." CalHFA says MyHome "must remain in second lien position," so the city loan would have to move behind it, and at the city's price limit the MyHome amount comes out under $50,000. As we read the rules today, MyHome and the city loan don't fit together; ask the city if you want both. For GSFA Platinum, ask us to check the numbers for your home.
Can I get a home equity line of credit later?
Not without the city's written consent while the city loan is open. The loan agreement says no additional mortgage or deed of trust, "including any line of credit," without it. Cash-out refinancing isn't allowed either.
Where can I get help in Spanish or Vietnamese?
The city's portal is available in English, Español and Tiếng Việt. Our team can help in English or Spanish with questions about the first mortgage: call 909.944.8800.
→ Read: CalHFA program page
Sources8 sources · show all
Every official site we use is also on one page: Official sources we use and trust.
Check each page directly. Program details change. All items below were read November 8 and 9, 2026.
- City of Anaheim, First-Time Homebuyer Program: https://www.anaheim.net/6695/First-Time-Homebuyer-Program
- City of Anaheim, Local Housing Trust Fund Program Guidelines, amended and adopted June 9, 2026 (First-Time Homeowners Program section): https://www.anaheim.net/DocumentCenter/View/66427 (copy saved November 8, 2026)
- City of Anaheim, housing portal: https://housingportal.anaheim.net/Fthb
- City of Anaheim, "My Anaheim Home First-Time Homebuyer Loan Program" flyer: https://www.anaheim.net/DocumentCenter/View/70637/My-Anaheim-Home---Program-Flyer---FINAL (read November 8, 2026)
- City of Anaheim, Housing & Community Development Department, email answers to our questions (lender list, combining programs, repayment, fourth-quarter 2026 price limit), November 9, 2026 (copy saved)
- City of Anaheim, Local Housing Trust Fund First Time Homebuyer loan document templates: loan agreement (template dated March 5, 2026), promissory note, deed of trust, Regulation Z disclosure; shared by the city November 9, 2026 (copies saved)
- Anaheim City Council minutes, March 24, 2026: https://local.anaheim.net/docs_agend/questys_pub/50119/50149/50150/50348/50418/50418.2.pdf
- CalHFA, MyHome program sheet (revised October 19, 2026): https://www.calhfa.ca.gov/homeownership/programs/myhome.pdf
- Golden State Finance Authority, participating lenders: https://gsfahome.org/programs/dpa/lenders.aspx
- HUD, housing counseling: https://www.hud.gov/counseling
Disclosures
Colleen Olivas, NMLS #379721. Robert Olivas, NMLS #271447. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
Down payment assistance programs have eligibility rules, funds are limited and subject to availability, and they are not available to everyone. Program terms, income limits, price limits and assistance amounts can change without notice. The My Anaheim Home program is run by the City of Anaheim, not by The Brandon Drew Group or New American Funding. This is for information only. It is not a commitment to lend or a rate quote. Loans are subject to credit approval and underwriting. Not tax or legal advice. For licensing information, visit www.nmlsconsumeraccess.org.