Buyer guide with Colleen Olivas
Dream For All Is Closed: What Are My Options in 2026?
By Colleen Olivas, NMLS #379721, who started in escrow and worked her way through every role in mortgages, up to underwriter. The Brandon Drew Group, a division of New American Funding Last reviewed November 2026
Quick answer
California's Dream For All program is closed to new applications. The 2026 window ended March 16, 2026, and CalHFA picked applicants by random drawing. If you were not selected, you may still have options: CalHFA MyHome Assistance, CalPLUS with ZIP, or GSFA Platinum. Subject to eligibility and availability.

Key points
- Dream For All is closed to new applications. The 2026 portal closed March 16, 2026, and CalHFA says no new applications can be submitted. CalHFA has not announced another round.
- CalHFA chose applicants by random drawing, not first come, first served. Not being chosen says nothing about your finances or your worth as a buyer.
- If you were not selected, CalHFA says you can still work with a CalHFA-approved lender and consider MyHome Assistance or CalPLUS with ZIP. GSFA Platinum is another program to review.
- The options repay differently. Dream For All shared the home's appreciation. MyHome is a deferred loan. GSFA Platinum's standard option has monthly payments. Know which one you are signing.
- Programs have income limits, occupancy rules and funds that are limited and subject to availability. Ask us for the current ones the day you call, and check the agency page too.
On this page (10 sections)
Opening
If you applied for Dream For All this year and did not get a voucher, you are not alone. CalHFA, the California Housing Finance Agency, expected $150 million to $200 million to be available for 2026. CalHFA chose who got help by random drawing, so meeting the rules did not guarantee a spot. That is hard news when you have already started picturing a front door.
It is not the end of the road. Dream For All was one tool. Others are open to buyers right now, and some of them may fit you well. They work differently, so the choice takes care.
This guide explains what Dream For All was, what happened in 2026, and what buyers who were not selected can do. It compares MyHome Assistance, CalPLUS with ZIP, and GSFA Platinum in plain words, and it shows you how to get your paperwork ready in case a new round opens. We can't tell you which option is right before we see your numbers. What we can do is help you ask better questions on your first call.
What was Dream For All?
Dream For All is a CalHFA program that gave first-time buyers down payment and/or closing cost help through a loan called a shared appreciation loan. "Appreciation" means the amount a home gains in value over time. A shared appreciation loan works like this. You borrow the assistance now. Later, when you sell the home, transfer it, or pay off your first mortgage, you repay the original amount plus a share of how much the home went up in value. It is not a gift. It is a loan with a different kind of cost. We leave out the exact shares and caps here because they change and depend on the loan. The program guide on calhfa.ca.gov has them.
Three things people get wrong about Dream For All:
"It was a grant." It was a loan. You repay it when the home is sold, transferred or the first mortgage is paid off, and part of the repayment depends on how much the home gained.
"First come, first served." For 2026 it was not. CalHFA ran a pre-registration window and then selected applicants by random drawing. Applying early did not improve your odds. Applying at all did.
"Everyone who qualified got it." Qualifying and being selected are two different things. A buyer could meet every rule and still not be drawn.
Who could apply
Based on CalHFA's program page, the rules included:
- You are a California resident.
- All borrowers are first-time buyers.
- Your household income is within the program's limit. CalHFA's current Dream For All income limit for San Bernardino County is $168,000 (effective June 30, 2026). It is lower than the limit for other CalHFA programs. Check CalHFA's page for the limit that applies to you.
- At least one borrower is a "first-generation" buyer. CalHFA defines this as a buyer who has not held an ownership interest in a home or a mortgage in the United States in the last 7 years, and whose parents (biological or adoptive) have no present ownership interest in a home in the United States, or who was placed in foster care or institutional care.
You also had to work with a CalHFA-approved lender. That is the term CalHFA uses for lenders that are cleared to offer its programs.
What happened in 2026
Here is the timeline from CalHFA's own pages.
| Date | What happened | Source |
|---|---|---|
| January 16, 2026 | CalHFA announced the 2026 round | CalHFA press release |
| February 24 to March 16, 2026 | Application window | CalHFA's January 16, 2026 announcement |
| March 16, 2026 | The 2026 portal closed | CalHFA Dream For All page |
| After the window | Applicants selected by random drawing; waitlisted applicants emailed if a voucher opens | CalHFA Dream For All page |
| May 20, 2026 | A note on CalHFA's page says "the next round of DFA vouchers have been released," and tells people who already applied to check the portal | CalHFA Dream For All page |
About the May 20 note
You may have seen a line on CalHFA's page, dated May 20, 2026, saying the next round of vouchers had been released. Here is how to read it. The note tells people who already applied to check their status in the Dream For All Portal. It is not a new application round. The same page says the portal closed on March 16 and no new applications can be submitted. CalHFA's January 16, 2026 announcement said no future rounds were planned.
If you applied, check your status in the DFA Portal yourself and watch your email, including your spam folder.
What are my options now?
If you were not selected, CalHFA's page says you can still work with a CalHFA-approved lender and consider MyHome Assistance or CalPLUS with ZIP. Past that, GSFA Platinum is another program to review. And there is the option of waiting for a possible future round of Dream For All.
Here is the short list:
- CalHFA MyHome Assistance. Down payment and closing cost help, paired with a CalHFA first mortgage.
- CalPLUS with ZIP. A CalHFA first mortgage plus a closing cost second loan called the Zero Interest Program (ZIP).
- GSFA Platinum. Help with down payment and closing costs from the Golden State Finance Authority.
- Waiting. A possible future Dream For All round, if CalHFA announces one. None has been announced.
- No assistance. Some buyers choose to keep saving and buy without a program.
Each one has trade-offs. The right question is not "which program is biggest?" It is "which program leaves me in the best position over the years I own this home?"
Comparing the options side by side
This table is a map, not an offer. Programs have eligibility rules, and funds are limited and subject to availability. Check the agency page in the last column on the day you decide.
Dream For All (closed)
- Who runs itCalHFA
- What it helps withDown payment and/or closing costs
- How it worksShared appreciation loan: repay the original amount plus a share of the home's gain
- When repaidOn sale, transfer or payoff of the first mortgage
- First-time buyer required?Yes, all borrowers
- Income limit, San Bernardino County$168,000
- StatusClosed. Check the portal
- Where to verifycalhfa.ca.gov/dream
MyHome Assistance
- Who runs itCalHFA
- What it helps withDown payment and closing costs
- How it worksDeferred second loan with simple interest; nothing is due until one of the events in the next row
- When repaidEarliest of sale or transfer, payoff or refinance of the first loan, or a recorded notice of default
- First-time buyer required?Yes
- Income limit, San Bernardino County$210,000
- StatusActive in CalHFA's January 1, 2026 matrices
- Where to verifycalhfa.ca.gov
CalHFA income limits shown here were effective June 30, 2026. Limits can change, so check the current ones. Sources and dates are in the Sources section.
Each option, one at a time
CalHFA MyHome Assistance
MyHome Assistance gives down payment and closing cost help to first-time buyers of an owner-occupied home in California. You must use a CalHFA-approved lender.
How it is built: it is a deferred-payment second loan. "Second" means it sits behind your main mortgage. "Deferred" means repayment waits while you hold the first loan. It carries simple interest. CalHFA says the rate will vary. You repay it at the earliest of these events: you sell or transfer the home, you pay off or refinance the first mortgage, or a Notice of Default is recorded and not rescinded. CalHFA also requires subordinate loans like this to be paid in full if the first mortgage is refinanced.
What to know:
- It must go with a CalHFA first mortgage. It pairs with CalHFA FHA, CalPLUS FHA, CalHFA Conventional, CalPLUS Conventional, CalHFA USDA and CalHFA VA.
- Buyer rules: no ownership of a principal residence in the past three years (including a spouse's home you lived in); everyone on the loan moves in within 60 days; no non-occupant co-borrowers or co-signers; U.S. citizen, national or qualified alien.
- It cannot pay off your debts, and you cannot receive cash back.
- Homebuyer education is required for one occupying first-time buyer per loan: the online eHome course, or a class through NeighborWorks or a HUD-approved counseling agency.
- The San Bernardino County income limit is $210,000. There is no sales price limit, but loan limits still apply.
- Credit and debt level follow the first mortgage. CalHFA publishes matrices for each loan type.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who want help with cash at closing and can meet the income and first-time buyer rules | It is a loan you will owe later, and it comes out of your proceeds when you sell | calhfa.ca.gov/homeownership/programs/myhome.pdf |
Read more: CalHFA MyHome Assistance, explained
CalPLUS with ZIP
CalPLUS is a CalHFA first mortgage that carries a slightly higher fixed rate than the standard CalHFA loan. CalPLUS FHA and CalPLUS Conventional must be used with ZIP. ZIP is short for Zero Interest Program, which is the program's name.
ZIP is for first-time buyers. It helps with closing costs and prepaid items only, not the down payment and not paying off debt. Any ZIP funds left over go to reduce your principal. It sits in third position, behind MyHome, so the two work together. Its term matches your first mortgage, and payments on it are deferred for the life of the CalPLUS first mortgage. It comes due at the earliest of a transfer of title, a payoff or refinance of the first mortgage, or a recorded Notice of Default (unless rescinded). CalHFA's programs page lists CalPLUS and ZIP.
The honest question is the trade. A slightly higher rate on the first mortgage is the cost of getting ZIP. Whether that trade is worth it depends on how long you plan to stay and what the whole package costs you. We lay it out on paper, side by side, with the standard CalHFA loan.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who need help with closing costs and want to pair it with MyHome | The first mortgage has a slightly higher fixed rate, so compare the whole package | calhfa.ca.gov |
Read more: CalPLUS with ZIP: is it worth it?
GSFA Platinum
The Golden State Finance Authority (GSFA) is a joint agency of California counties and cities. GSFA is not a direct lender. It works through what it calls "GSFA Participating Lenders." GSFA lists New American Funding, LLC as a participating lender for GSFA Platinum.
GSFA Platinum offers down payment and closing cost help for the purchase or refinance of a primary residence in California. There is no first-time buyer requirement. That is a real difference from Dream For All and MyHome. It works with FHA, VA, USDA and conventional first mortgages. GSFA says credit scores as low as 640 may qualify, debt-to-income ratios (your monthly debts compared with your income) up to 50 percent may qualify, and the maximum first mortgage is $832,750.
The standard option is a fully amortizing second mortgage. "Fully amortizing" means you make regular monthly payments that pay it off. Those payments are at the first mortgage rate. That is very different from a deferred loan. You get the help now, and you pay it back monthly alongside your main mortgage, so it affects your monthly budget.
GSFA set no income limits for FHA, VA or USDA first mortgages through its programs. Limits for conventional first mortgages are set by county. See GSFA's limits page for the current figures.
It also lists an Assist-to-Own option for employees of GSFA member counties, repaid to GSFA when the first mortgage is sold or refinanced. Ask GSFA (855-740-8422) whether your county is a member.
| Best for | The catch | Where to verify |
|---|---|---|
| Buyers who are not first-time buyers, or who fit GSFA's job-based options | The standard second loan has monthly payments, so look at the total monthly picture | gsfahome.org/programs/dpa/platinum.shtml |
Read more: GSFA Platinum: how it works and what to compare
Waiting for a possible future round
CalHFA has not announced another round, and the May 20 note applies to people who already applied (see above). We will not predict if or when funds return, and you should not plan your purchase around it. If you are waitlisted, watch your email.
What you can do while you wait is use the time. Review your credit, keep your savings in a clear paper trail, finish the homebuyer education class, and gather your documents. Those steps help whichever route you take.
Not using a program at all
Some buyers decide they do not want a second loan. Some do not meet the income or first-time buyer rules. That is a fine choice if the numbers work. You keep more freedom in your first mortgage and owe nothing extra to a program. The cost is that you need more cash up front. San Bernardino County's housing office says it no longer offers down payment assistance and points residents to CalHFA and outside agencies, so the programs above are the main places to look. The City of Rancho Cucamonga's housing page lists no down payment program either.
A worked example, in words
This example is made up. The person, the home and the numbers are not real. It uses no numbers on purpose.
Suppose a buyer, "Maria" (a made-up name), applied for Dream For All, passed the first-time buyer test, and was not drawn. She is disappointed, and she asks us what happens next.
Here is how a first conversation might go. We ask about her household income and compare it with each limit. We ask how long she expects to stay in the home. We ask what she can comfortably pay each month, and how much cash she has saved.
Then we sketch the three routes on one page.
With MyHome, she gets a deferred second loan. Her monthly budget stays lighter now, but the amount she owes grows with interest and comes due when she sells or refinances. If she plans to stay many years, she asks how the balance may look by then.
With CalPLUS and ZIP, she gets help with closing costs. The trade is a slightly higher rate on her first mortgage. If she plans to refinance in a few years, she asks how that interacts with the second loan.
With GSFA Platinum, she gets help with the down payment and closing costs, but the standard second loan has a monthly payment. Her cash at closing is easier, but her monthly budget has to carry more.
Maria does not pick the biggest number. She picks the route that fits her income, her plans and her comfort. If none fits yet, she picks a plan to get ready, and we talk again in a few months. That is a good outcome too.
How to get ready in case Dream For All reopens
If CalHFA opens another round, there may be a short window and a long line. We cannot predict that. We can tell you what to do now, so you are not scrambling.
- Confirm the program rules. Read CalHFA's Dream For All page, including the first-generation buyer definition and the income limit for your county.
- Work with a CalHFA-approved lender now. Programs are only offered through one. A lender who knows your file can help you watch for a new window.
- Gather your documents. Pay stubs, tax returns, bank statements and an ID. Keep your statements clear; large transfers need an explanation.
- Take homebuyer education. MyHome Assistance requires it. The online eHome course takes about eight hours. Doing it early removes a step later.
- Check your credit. Pull your free reports and fix errors early. Credit and debt follow the first mortgage, so the first loan's rules apply.
- Watch the official portal and your email. Check the CalHFA Dream For All page yourself. If you registered before, watch your email and spam folder.
- Do not wait to buy if another route fits. If a route fits you now, a possible future round is not a reason to hold off. That is your decision, and we will help you think it through, but no one can promise a reopening.
Mistakes we want you to avoid
Assuming "not selected" means "not qualified." The drawing was random. You may still qualify for other programs.
Reading the May 20 note as a new application round. It tells people who already applied to check the DFA Portal. No new applications can be submitted.
Comparing only the assistance. A program can look generous and still sit on a first mortgage that costs more over time. Compare the whole loan.
Missing the income-limit difference. Dream For All's limit is lower than the limit for other CalHFA programs. Being out of one limit does not put you out of another.
Ignoring what comes due later. Deferred does not mean forgiven. Ask when and how it is repaid, and what it takes out of your sale proceeds.
Waiting too long to ask. Funds are limited. A call costs nothing, and asking early gives you more time to plan.
How to decide
Do not start with the program name. Start with these four questions.
1. Am I within the income limit? Limits differ by program and county. If you are near one, tell us early.
2. Am I a first-time buyer under the program's rule? MyHome and Dream For All required it. GSFA Platinum does not.
3. How long do I plan to stay? A deferred loan comes due at sale or refinance. A loan with monthly payments changes your budget every month. We show you how each behaves under your plan, without predicting the future.
4. What does the whole package cost me? Ask for a plain page that shows what you will owe, when, and to whom, for the assistance and the first mortgage together.
The bottom line
Dream For All is closed, and the 2026 round was decided by random drawing, so not being chosen was not a judgment on you. CalHFA says you can still look at MyHome Assistance and CalPLUS with ZIP, and GSFA Platinum is another program to review. Each one repays differently, so compare them on paper before you choose.
If you want to be ready in case Dream For All returns, get your documents together, take the homebuyer class, and check CalHFA's official page. Call us when you are ready. We will give you straight answers, including "not yet."
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
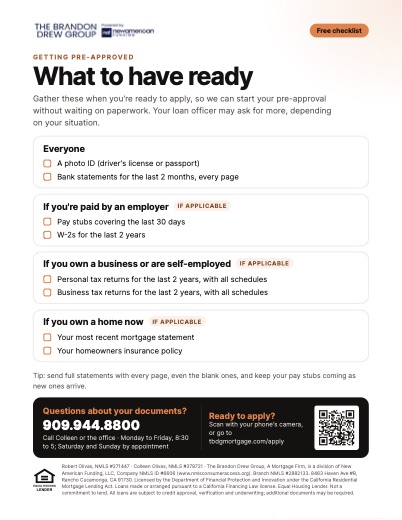 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
Is Dream For All still open?
No. CalHFA lists Dream For All as closed to new applications, and the 2026 portal closed March 16, 2026. CalHFA says no new applications can be submitted, and it has not announced another round. The page does carry a May 20, 2026 note that the "next round" of vouchers was released. That note is for people who already applied, who should check their status in the DFA Portal. It is not a new application round.
Why was I not selected for Dream For All?
CalHFA selected applicants by random drawing, not first come, first served. Meeting the rules did not guarantee a spot, and applying early did not raise your odds. Being left out says nothing about your credit or readiness. It means the drawing did not select you. Waitlisted applicants are emailed if a Dream For All voucher opens.
What can I do if I was not selected for Dream For All?
CalHFA says applicants who were not selected can still work with a CalHFA-approved lender and consider MyHome Assistance or CalPLUS with ZIP. GSFA Platinum is another program to review. Each has its own rules, income limits and way of being repaid, so compare them side by side with a lender who offers them. You can also keep saving and watch for a possible future Dream For All round. Subject to eligibility and availability.
How is Dream For All different from MyHome Assistance?
Dream For All was a shared appreciation loan. You repay the original amount plus a share of the home's gain when you sell, transfer or pay off the first mortgage. MyHome is a deferred second loan with simple interest. You repay it at the earliest of a sale, transfer, payoff or refinance of the first loan, or a recorded notice of default that is not rescinded. The income limits also differ for San Bernardino County: $168,000 for Dream For All and $210,000 for MyHome.
Does GSFA Platinum require me to be a first-time buyer?
No. GSFA says there is no first-time buyer requirement for Platinum, but it is for a primary residence only, and it works through GSFA Participating Lenders. The standard option is a second mortgage with monthly payments, which is different from a deferred loan. GSFA says credit scores as low as 640 may qualify, but your lender and the first mortgage set their own rules. GSFA lists New American Funding, LLC as a participating lender for Platinum.
How do I find a CalHFA-approved lender?
CalHFA's programs are offered through CalHFA-approved lenders. CalHFA has a lender search at calhfa.ca.gov/apps/approvedlenders, and you can call CalHFA at 877-922-5432. CalHFA also keeps a "Find a Loan Officer" list of CalHFA-trained loan officers (calhfa.ca.gov/homebuyer/lenders.htm), so you can check a name before you call. CalHFA notes that a branch may or may not have loan officers on site who are trained to process its loans. Before you work with any lender, ask whether it is approved for the program you want and ask the loan officer to show you the current rules. Colleen is listed on CalHFA's website as a CalHFA Preferred Loan Officer.
Should I wait for Dream For All to reopen?
That is your decision, and no one can promise a new round. CalHFA has not announced one. If another option fits you now, waiting for a program that may not return carries a risk of its own. If nothing fits yet, use the time to get ready: documents, homebuyer class, credit and savings. We will tell you honestly which makes more sense for your situation.
Sources18 sources · show all
Check each page directly. Program details change. All items below were checked October 28, 2026.
- CalHFA, Dream For All: https://calhfa.ca.gov/dream/
- CalHFA press release, January 16, 2026: https://calhfa.ca.gov/about/press/press-releases/2026/pr2026-01-16.htm
- CalHFA, MyHome Assistance Program: https://www.calhfa.ca.gov/homeownership/programs/myhome.pdf
- CalHFA, homebuyer education (MyHome): https://cloud.calhfa.ca.gov/homebuyer/programs/myhome.htm
- CalHFA, programs overview (CalPLUS and ZIP): https://cloud.calhfa.ca.gov/homebuyer/programs/index.htm
- CalHFA, income limits: https://cloud.calhfa.ca.gov/homeownership/limits/income/income.pdf
- CalHFA, Dream For All income limits: https://calhfa.ca.gov/homeownership/limits/income/income-cadfa.pdf
- CalHFA, loan and price limits: https://calhfa.ca.gov/homeownership/limits/index.htm
- CalHFA, ZIP terms (government loan handbook): https://www.calhfa.ca.gov/homeownership/programs/loans-gov.pdf
- CalHFA, programs (CalPLUS line-up): https://www.calhfa.ca.gov/homebuyer/programs/index.htm
- CalHFA, first-generation buyer definition: https://www.calhfa.ca.gov/homebuyer/borrower.htm
- CalHFA, refinance and subordinate loans: https://www.calhfa.ca.gov/homeownership/programs/refi.htm
- CalHFA, approved lender search: https://www.calhfa.ca.gov/apps/approvedlenders
- CalHFA, Find a Loan Officer: https://calhfa.ca.gov/homebuyer/lenders.htm
- Golden State Finance Authority, GSFA Platinum: https://gsfahome.org/programs/dpa/platinum.shtml
- GSFA, participating lenders: https://gsfahome.org/programs/dpa/lenders.aspx
- GSFA, income limits: https://gsfahome.org/programs/dpa/limits.aspx
- County of San Bernardino, home ownership resources: https://cdh.sbcounty.gov/home-ownership-resources/
Disclosures
Colleen Olivas, NMLS #379721. Robert Olivas, NMLS #271447. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
Down payment assistance programs have eligibility rules, funds are limited and subject to availability, and they are not available to everyone. Program terms, income limits, price limits and assistance amounts can change without notice. This is for information only. It is not a commitment to lend or a rate quote. Loans are subject to credit approval and underwriting. Not tax or legal advice. Examples are made up and for illustration only. For licensing information, visit www.nmlsconsumeraccess.org.